Self-Driving Cars in 2026: Robotaxis Expand While Consumer Autonomy Lags
Waymo, Zoox, and Tesla are scaling driverless and supervised miles, but most consumer vehicles remain Level 2 or 3. Vision-based, map-free systems and new partnerships are cutting costs, while safety incidents and regulation keep trust fragile.
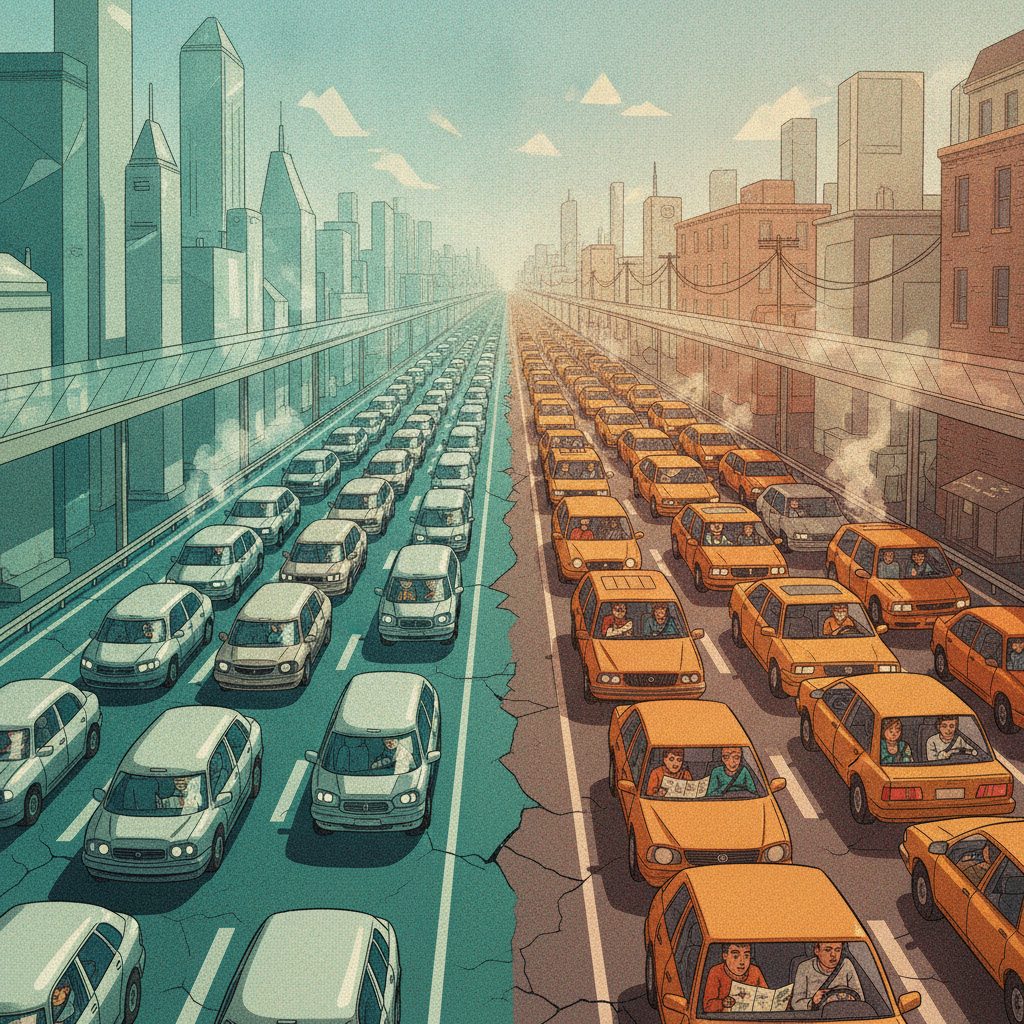
In 2026, the autonomous vehicle industry is no longer selling a distant vision. Waymo has logged more than 100 million rider-only miles and now provides about 250,000 rides per week, while Tesla reports 6.9 billion supervised miles under its Full Self-Driving system. Zoox, Amazon’s autonomous unit, began public robotaxi rides in Las Vegas in September 2025 and is expanding to San Francisco with steering-wheel-free vehicles. At the same time, most consumer cars remain at SAE Level 2 or Level 3, meaning drivers must still supervise or be ready to take over, even as Level 4 robotaxis operate in geo-fenced urban areas. The gap between consumer assistance and commercial autonomy defines the current moment.
For executives and founders, this is not just a technology story. AI-driven autonomy represents a convergence of scalable software, mass-market vehicle platforms, and strategic partnerships such as Pony.ai–Toyota and Honda–Helm.ai. The move toward vision-based, map-free systems could lower infrastructure costs and speed deployment. But safety scrutiny and regulatory hurdles remain critical risks for investment and public trust. A single high-profile incident can shift timelines and reshape liability frameworks, making the sector’s progress uneven and highly watched.
The 2026 Deployment Landscape: From Supervised Miles to Driverless Fleets
Waymo, a subsidiary of Alphabet, remains the commercial leader. Its robotaxis operate in Las Vegas and are expanding to San Francisco, with more than 100 million rider-only miles accumulated and roughly 250,000 rides per week as of 2026. Zoox, owned by Amazon, launched its robotaxi service in Las Vegas in September 2025 and is now moving into San Francisco with bidirectional, steering-wheel-free vehicles powered by NVIDIA AI. Tesla, by contrast, is a challenger at scale, leveraging its global fleet data for vision-only Full Self-Driving. The company reports 6.9 billion supervised miles under FSD and has its Cybercab in production.
Other players are moving quickly. Pony.ai targets deployment of more than 3,000 robotaxis by the end of 2026 using its Gen 7 hardware, which reduces costs by 70 percent compared to prior versions. Aurora has focused on Level 4 autonomous trucking and launched commercially in April 2026 using PACCAR and Continental technology. According to industry tracking, Waymo, Aurora, Tesla, Pony.ai, and WeRide together account for more than 70 percent of global robotaxi activity. Most consumer vehicles, however, still operate at SAE Level 2 or Level 3, while Level 4 robotaxis remain confined to geo-fenced urban areas.
The distinction between SAE levels matters. Level 2 systems require the driver to remain fully engaged, while Level 3 allows eyes-off driving under specific conditions but still requires a human to take over when prompted. Level 4, used by robotaxis, can operate without a human driver in defined areas. This gap explains why consumer vehicles and commercial robotaxis are evolving on different timelines.
The Technology Shift: Vision-Based, Map-Free Systems and Affordable Autonomy
A significant technical shift is underway toward vision-based, map-free autonomous systems that do not rely on lidar or high-definition maps. Helm.ai, a U.S.-based AI startup, is developing full-stack, vision-based autonomous systems and has partnered with Honda and Volkswagen. Honda, in collaboration with Helm.ai, plans to release AI-equipped hybrid and electric vehicles with autonomous capabilities in fiscal 2027. This approach could reduce the cost and complexity of deploying autonomy in new regions, since it avoids the need for continuously updated HD maps and expensive lidar arrays.
Ford is targeting affordable autonomy through its Universal Electric Vehicle platform, aiming for mass-market Level 3 “eyes-off” autonomy by 2028 on a $30,000 vehicle. That price point would mark a significant step toward democratizing access to advanced driver assistance. Audi is taking a more incremental path, enhancing Level 2 ADAS with augmented reality overlays for navigation and hazard alerts in 2026 models. Tesla’s vision-only FSD is another example of the map-free direction, relying on camera inputs and neural networks rather than pre-mapped environments. Together, these efforts point to a future where autonomy is not limited to premium vehicles or dense urban robotaxi fleets.
Safety, Regulation, and the Trust Deficit
Progress is tempered by safety concerns and regulatory scrutiny. In January 2026, a Waymo autonomous vehicle in Santa Monica hit a child who ran into the street from behind a double-parked SUV. The vehicle was operating without a safety driver and reduced its speed from 17 mph to under 6 mph before impact, according to reports. The U.S. National Highway Traffic Safety Administration is investigating whether Waymo exercised appropriate caution near a school. Such incidents underscore ongoing safety and liability questions, even as AI improves perception and response times.
Adoption timelines are lengthening due to technical, regulatory, and safety challenges. While robotaxi deployments in geo-fenced areas have expanded, the path to broad consumer autonomy remains uneven. Regulators are paying closer attention to how autonomous systems behave in complex, unpredictable environments such as school zones and residential streets. The NHTSA investigation is one of several regulatory actions globally that could influence how autonomous vehicles are deployed near schools, crosswalks, and other high-risk areas. For companies, this means that engineering progress alone is not enough; building public trust and demonstrating transparent safety practices are now central to commercial viability.
Strategic Implications for Industry Leaders
For executives and founders, the autonomous vehicle market in 2026 presents a dual reality. On one side, scalable technology and strategic partnerships are lowering costs and accelerating deployment. Pony.ai’s collaboration with Toyota, Honda’s work with Helm.ai, and Ford’s affordable UEV platform all point toward mass-market accessibility. Vision-based, map-free systems could reduce infrastructure costs and make autonomy viable in more regions. On the other side, safety incidents and regulatory investigations can delay launches, increase liability exposure, and erode consumer confidence.
The business models are diverging. Robotaxi operators such as Waymo and Zoox are pursuing Level 4 services in controlled urban areas, while automakers like Ford and Honda are bringing Level 2 and Level 3 features to consumer vehicles. Tesla sits between these models, using its large fleet of supervised vehicles to train vision-based FSD while producing the Cybercab. For investors and partners, the key questions are no longer whether AI can drive a car, but whether it can do so safely, affordably, and within a regulatory framework that supports scale. The incident in Santa Monica also highlights the need for robust remote monitoring and clear liability frameworks, which remain unresolved in many jurisdictions.
Looking ahead, the next 24 to 36 months will test whether autonomous driving can move from geo-fenced demonstrations and supervised data collection to profitable, safety-accepted deployment at scale. The industry’s leaders are betting on lower-cost hardware, vision-based perception, and strategic manufacturing partnerships to reach mass-market price points. But the outcome will depend as much on regulators, insurers, and public acceptance as on AI performance. If the current trajectory holds, Level 4 robotaxis and Level 3 consumer vehicles could become a meaningful part of global mobility by the late 2020s—yet every incident will continue to shape the speed and shape of that transition.
Sources
- AI in Self-Driving Cars: Revolutionizing the Future of Autonomous Vehicles
- AI in Self-Driving Cars
- Artificial Intelligence in Autonomous Vehicles - Imagination
- Self-driving car
- Self driving cars, a technology that could change the world - Duckietown
Written by an AI editorial process from the sources above. Errors may occur.
Newsletter
Get the AI news that matters
One short brief with the day's most important AI stories — written for professionals.
We send a confirmation link. No spam. Unsubscribe anytime.
Read next
The AI Cloud Race: Big Tech's $130B Power Play
Amazon, Microsoft, and Alphabet are spending billions to dominate AI through cloud infrastructure, reshaping global tech, security, and market dynamics.
19 Sep 2026
AI Inference Market to Hit $255B by 2030
Global demand for real-time AI decision-making drives explosive growth in inference infrastructure, with NVIDIA, Intel, and Siemens Healthineers leading diverse applications.
18 Sep 2026
Autonomous AI Agents Become Core Enterprise Infrastructure in 2026
The market for autonomous AI agents is projected to surge from $7.92 billion in 2025 to $236.03 billion by 2034, as enterprises shift from experimentation to governing systems that perform operational work.
14 Sep 2026